Seven business insurance costs beyond the premium in England: IPT at 12% or 20%, fees, finance, excess, uninsured loss, controls and time, with a worked total.
A business insurance budget template for England: premium, Insurance Premium Tax at 12%, fees, excesses and a cash schedule, with the rules behind each line.
Key business insurance metrics for England with sources: 12% Insurance Premium Tax, the eight-week complaint clock, claims timing and Cyber Essentials from £320.
The Windsor Framework changes customs, not insurance law. Named rules apply: employers' liability in GB and Northern Ireland, fair presentation, FCA register.
A dated UK rule calendar for business insurance to 2027: PS25/21, CP25/37 rules, the CP26/22 consultation and PS26/2 incident reporting, plus PII limits.
How to run business insurance after purchase: register check, employers' liability certificate, claims log under ICOBS 8.1 and the eight-week complaint clock.
Define a business insurance target audience in England using official business counts, employers' liability triggers, buying roles and the FCA PROD 4.2 test.
Business insurance for UK small firms should match seasonal risks: winter freeze, summer flooding and event cancellation, with cover checked each season.
Commercial insurance in Manchester, Birmingham and Glasgow: how local broker expertise, insurer appetite and SME pricing differ across the three cities.
Commercial insurance for small businesses in England: how a Scottish link can change claim deadlines, Scottish courts and policy wordings for English SMEs.
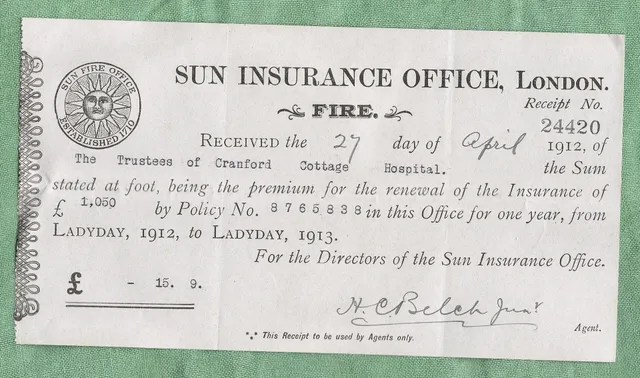
Commercial insurance prices in the UK carry Insurance Premium Tax at 12% or 20%, while VAT usually does not apply. Here is how each tax changes your premium.
Commercial insurance and Flood Re: what the scheme covers for homes and small firms, its exclusions for larger property, and how flood maps shape cover in England.
Employers' liability insurance in Great Britain: who needs cover, the £5 million minimum under the 1998 Regulations, family exemption and certificate duties.
How a small business owner should evidence a commercial insurance claim after a break-in, from the crime reference number to photographs, invoices and stock reports.
Commercial combined insurance bundles liability, property and interruption cover into one package policy. Here is what UK packages include and when standalones win.
Home insurance often excludes business stock, visiting clients and equipment. Check what UK home-based businesses must declare, and when separate cover is needed.
Van tool insurance for tradesmen: what policies usually cover, the exclusions that cause declined claims, and how to check a tool cover add-on before you pay.
How to run business insurance agency reviews England: verify the broker's identity, FCA permissions, insurer market, fees and claims role before you commit.
Practical business insurance AI applications for UK firms: intake extraction, document comparison, triage and claims support, with UK GDPR and FCA controls.
Business insurance attribution methods for small firms: connect quote, policy and service outcomes to their sources without claiming unsupported causation.
Match a firm to one of five business insurance routes in England, AXA, Hiscox, Direct Line, Aviva or Simply Business, with the caution to test for each.
Research business insurance buyer personas: test profiles, record behaviours and exposures, assign confidence levels and connect findings to product governance.
Review eight business insurance clauses in commercial contracts governed by English law, from required limits and insured parties to claims cooperation.
An illustrative £1,000 business insurance premium in England worked into its full cost: Insurance Premium Tax, broker fee, finance charge, excess and reserve.
A practical UK method for budgeting business insurance costs and pricing, separating quoted charges, payment finance, controls, excesses and retained losses.
Use seven observable business insurance demand signals in England, from employing staff and driving for work to contracts, premises and cyber exposure.
Bank of England data gives 2023 gross written premiums of £4.746 billion for commercial motor, £27.174 billion for commercial property and £25.705 billion for general liability — £57.625 billion across the three lines together. The figures are UK-wide, cover all firm sizes, and contain no England small-business total.
Run days 46 to 90 of a business insurance plan in England: send one controlled fact set, compare quotations, check the issued policy and test the response.
Use a practical business insurance planning template for England, covering exposures, controls, disclosure, policy checks, ownership and review triggers.
Use this business insurance quality checklist to review small-business policy records, test servicing controls and document failures in a consistent audit.
Assess business insurance return on investment through loss scenarios, policy response, costs, continuity and total cost without inventing a percentage.
Compare business insurance routes when planning for 2027 in England by checking roles, contract terms and cost evidence, with provider examples and a review method.
Five business insurance risk scenarios — cyber, premises, AI, supplier and injury — to test detection, notification, evidence and the policy questions raised.
A UK small-business insurance selection checklist to verify the FCA Register, compare policy documents, separate premium, tax and fees, and record the decision.
Set commercial insurance service standards from customer harm and capacity, keep them separate from regulatory deadlines, measure quality, record exceptions openly.
Avoid eight business insurance strategy mistakes in England, from planning by policy name to weak disclosure records and untested recovery assumptions.
Business insurance supplier comparison for brokers selecting software: match workflows, apply pass/fail gates, assess evidence and test migration before award.
A practical guide to business insurance tool implementation for small firms: prepare policy records, control access, test workflows and retain a fallback.
Which business insurance is compulsory in England: employers' liability, motor third-party cover, and the cover a regulator, licence or contract can require.